Skip to content
By Edward Parsons, CPA | Ed Parsons CPA, Doral, Florida | Representing taxpayers nationwide
A PFIC, or Passive Foreign Investment Company, is a foreign corporation that earns most of its money from passive sources or holds mostly passive assets. The most common examples are non-U.S. mutual funds and ETFs. If you are a U.S. taxpayer who owns one, the IRS taxes it under special rules that are much harsher than the rules for an American fund, and you generally must report each holding every year on Form 8621. Which way a fund is taxed comes down to an election, and the three regimes are compared in QEF vs mark-to-market vs Section 1291.
Most people who run into PFIC rules never set out to buy anything exotic. They opened a brokerage account in another country, bought a local mutual fund, or simply kept investments from a place they used to live.
The surprise comes later. A fund that looks completely ordinary overseas can be one of the most heavily taxed assets a U.S. person is able to hold.
This guide explains what a PFIC is, how the IRS decides whether you own one, why the tax treatment is so steep, and what your choices are if you have years that were never reported.
How a Foreign Corporation Becomes a PFIC
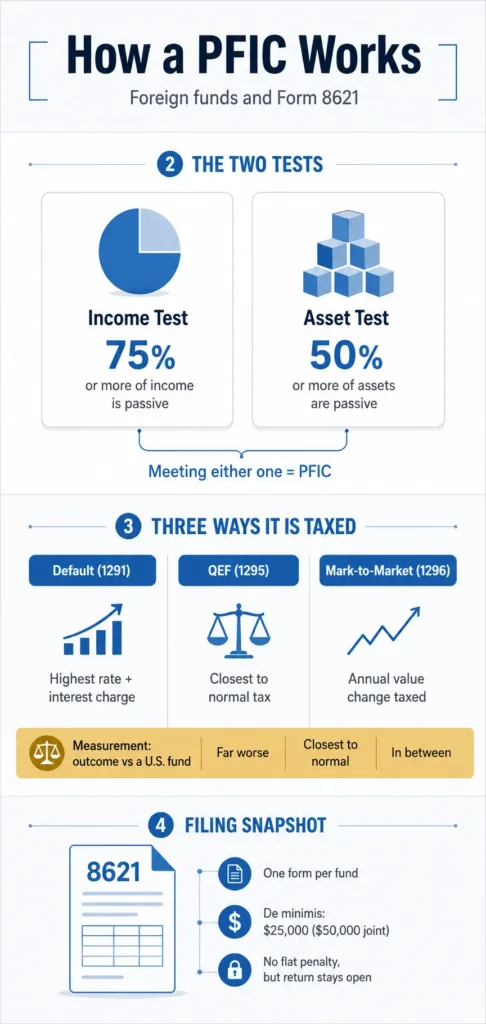
A foreign corporation is treated as a PFIC if it meets either of two tests in a given tax year. Only one of them has to be true.
- Income test: 75% or more of the company’s gross income is passive, meaning interest, dividends, rents, royalties, or capital gains.
- Asset test: at least 50% of the company’s assets produce passive income or are held to produce it.
Because the tests are applied year by year, a company can move in and out of PFIC status over time. Once you are treated as owning PFIC stock, continuation rules can keep that treatment in place even after the fund itself changes.
The numbers worth remembering are short:
- Income test trigger: 75% of gross income is passive.
- Asset test trigger: 50% of assets are passive.
- Tested: every single tax year.
- Reported on: Form 8621, one for each fund.
Why PFIC Status Matters
The default tax treatment is the reason PFICs have such a bad reputation. Under it, gains and unusually large distributions are spread back across every year you owned the fund and taxed at the highest ordinary rate, with an interest charge added as if the tax had been due all along.
There is no long-term capital gains rate under the default method, and the math often eats a large share of the return. Two elections can soften this, but each comes with its own conditions.
The table below compares the three ways a PFIC can be taxed. The choice between QEF and mark-to-market usually has to be made early, which is part of why timing matters.
| Feature | Default (Section 1291) | QEF (Section 1295) | Mark-to-Market (Section 1296) |
| How it taxes you | Gains and large distributions are spread back across your holding period | Your share of the fund’s ordinary income and capital gain, reported each year | The annual change in market value, reported as income |
| Rate character | Highest ordinary rate applied year by year | Ordinary and capital gain character preserved | Ordinary income, with limited ordinary losses |
| Interest charge | Yes, added on top of the tax | No | No |
| When you choose it | No election needed (this is the fallback) | First year, and the fund must supply annual data | First year you file for the fund |
| Information needed | Full distribution and sale history | PFIC Annual Information Statement from the fund | Reliable year-end market values |
| Measurement: outcome vs a U.S. fund | Far worse | Closest to normal | In between |
The default method applies whenever no valid election is in place, so doing nothing is itself an expensive choice.
Common Investments That Turn Out to Be PFICs
Most PFICs are not unusual products. They are everyday investments that happen to be organized outside the United States.
- Foreign mutual funds and unit trusts.
- Foreign ETFs and index funds.
- Pooled funds held inside foreign pension or insurance wrappers.
- Foreign hedge funds and money market funds.
- Certain foreign holding companies and startups with mostly passive assets.
Retirement-style and savings accounts in other countries often hold these funds inside them, which is why expats and newer U.S. residents are caught off guard so often.
If your own fund appeared in that list, the next question is not really whether it qualifies but what the classification costs you. That is the ground the five short emails I send on PFICs cover: the two tests that pull a fund in, the default method that taxes gains at the top ordinary rate no matter how long you held them and adds an interest charge reaching back across the whole holding period, and the two elections that can replace it where the timing still allows. Send me the five PFIC emails. There is a confirmation email first, and the series waits until you click it. Unsubscribe from any of them.
Who Has to File Form 8621
Filing happens at the shareholder level, and the IRS expects a separate form for each PFIC you hold. You generally have to file in any year where one of the following is true:
- You received a distribution from a PFIC.
- You sold or otherwise disposed of PFIC stock at a gain.
- You made, or are reporting, a QEF or mark-to-market election.
You are required to file an annual report under Section 1298(f). The IRS lists these triggers on its About Form 8621 page.
A limited exception can reduce the burden for very small holdings, but it is narrower than people assume:
- De minimis exception: total PFIC value of $25,000 or less ($50,000 for married filing jointly).
- Indirect ownership through another PFIC: the threshold drops to $5,000.
- The exception does not apply if you received an excess distribution, sold shares at a gain, or made an election in that year.
There is no flat dollar penalty for skipping Form 8621, but the consequence can be worse: an unfiled form can keep your entire tax return open to IRS review indefinitely. When a fund applies to you, working with a CPA on Form 8621 PFIC filing is the cleaner path than guessing. The pieces of this each have their own guide: whether you need to file Form 8621 at all, the asset test and the income test, the excess distribution regime, why the status sticks once a fund qualifies, and catching up when years were missed.
What Changed on the Latest Form 8621
The IRS issued a revised Form 8621 dated December of last year, and the changes are easy to miss if you reuse prior-year entries.
- Part V was restructured for distributions and dispositions.
- A new line requires a three-letter currency code.
- A new line asks filers to report a related amount converted into U.S. dollars.
Filers who copy figures onto the wrong lines can create errors that are hard to unwind later. The current Form 8621 instructions describe the new fields in detail.
Part V is also where the arithmetic lives. Before a single line can be filled in, every distribution has to be measured against the three years before it, and every sale has to be spread across the days you held the shares. The PFIC Calculator does that from the transactions your broker already reports: it tests each fund year by year, works out the section 1291 tax and interest, and fills in the official Form 8621 for every fund and every year, with workpapers that show where each figure came from.
Common Mistakes
These are the patterns that turn a manageable situation into a costly one:
- Assuming a foreign fund is taxed the same way as a U.S. mutual fund.
- Skipping Form 8621 in a year with no income, when filing was still required.
- Filing one form for several funds instead of one form per fund.
- Missing the first-year window to elect QEF or mark-to-market treatment.
- Treating the $25,000 exception as a free pass after a sale at a gain or an excess distribution.
- Believing there is no downside because there is no flat dollar penalty.
Questions People Ask
“I only have one small foreign fund. Do I really have a PFIC?”
Possibly, yes. Size does not change whether a fund is classified as a PFIC. It can only affect whether a limited filing exception applies.
“There is no penalty for skipping Form 8621, so why bother?”
There is no flat dollar penalty, but leaving the form unfiled can keep your whole tax return open to IRS review with no clear end date. That open window is the real exposure.
“Can I just sell the fund and move on?”
A sale can trigger the default tax regime and a filing obligation for that year, so selling often creates the very problem people are trying to leave behind.
If You Have Unreported PFIC Years
Discovering a PFIC after the fact is common, and there are established ways to get current. The right path depends on how many years are involved, whether income was reported, and whether any elections are still available.
Catching up is rarely fill-in-the-blank, because the default calculations look backward across your full holding period and a late election can lock in the harshest treatment.

Talk to a CPA about your PFIC situation.
A focused review can confirm whether your funds are PFICs, identify which years need attention, and map the lowest-risk way forward. Start with a CPA tax resolution case analysis.
Not sure your fund even qualifies?
Run it through the PFIC Analyzer to check the income and asset tests before you decide what to do next.