Skip to content

Filing an FBAR late does not trigger an automatic penalty. You file the missed FinCEN Form 114 the same way as a timely one, through the BSA E-Filing System, and the form asks you to state why it is late. Whether a penalty follows depends on two things: whether every dollar of income from those accounts is already on your tax returns, and whether your reason amounts to reasonable cause.
The program that used to make the first case simple, the Delinquent FBAR Submission Procedures, has been withdrawn. If your income was fully reported, a late FBAR now rests on the reasonable-cause statement you file with it. If income went unreported, exposure starts at $16,536 per late report and streamlined filing becomes the repair path.
Which side of that line you are on is the only question that matters, and it is answered by your tax returns, not by the FBAR itself.
Update: the IRS has withdrawn the Delinquent FBAR Submission Procedures. The programme’s page on irs.gov now returns an error, and the IRS list of options for taxpayers with undisclosed foreign financial assets names only three routes: the Criminal Investigation Voluntary Disclosure Practice, the Streamlined Filing Compliance Procedures, and the delinquent international information return submission procedures, which is a separate programme for information returns rather than FBARs. This page has been rewritten for the rules as they stand now. If you need this looked at on your own facts, request a quote or contact me directly.
This guide covers the real penalty numbers, what a reasonable-cause statement has to establish, the reasons that hold up, and a decision tree for the routes that remain.
What Is the Penalty for Filing an FBAR Late?
There is no late fee for an FBAR the way there is for a tax return. The Bank Secrecy Act penalties attach to the failure to file, and the IRS asserts them after review, not automatically. The reporting rules sit on the IRS FBAR page.
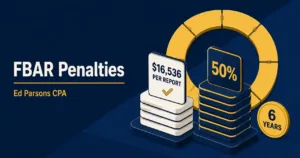
The numbers are severe. Non-willful violations run $16,536 per report at the current inflation-adjusted rate, and under Bittner v. United States that is per report, not per account. Willful violations reach the greater of $165,353 or 50 percent of the account balance.
The ceiling is real. In United States v. Schwarzbaum (11th Cir.), a willful FBAR assessment of $12.5 million was trimmed by only $300,000 as an excessive fine under the Eighth Amendment. The Justice Department declined to seek Supreme Court review, and the First Circuit has ruled the other way, so full exposure remains the working rule.
Here is what the penalty numbers hide: late filers who correct through the right IRS lane usually pay none of this. The lane depends on one fact, whether the income was reported.
That one fact does more work than anything else on this page, and getting it wrong is where most of the expensive outcomes I see begin. The five emails I send on FBARs spend real time on it: how far back a catch-up has to reach, which route fits when no additional tax is owed and which when income went unreported, and what happens to your relief when the wrong door gets used or a quiet filing is stacked on top of it. Send me the five FBAR emails. A confirmation note goes out first and the series waits on your answer to it. Unsubscribing is one click from any email.
Can You File a Late FBAR Without Penalty?
There is no longer a program that promises it. While the Delinquent FBAR Submission Procedures were open, the IRS said it would not penalize late reports where all foreign income was reported, the tax was paid, and you had not been contacted. That assurance is gone.
What remains is the rule the assurance sat on top of. The IRS manual still tells examiners not to assert a penalty where the failure was not willful, was due to reasonable cause, and the account is properly reported on the late FBAR (IRM 4.26.16.3.11). The difference is that nobody decides this in advance. You file, you state your reason, and the question is only answered if the IRS looks.
Getting the reports themselves right, maximum balances, currency conversions, account types, is what the Form 114 FBAR CPA Filing service covers. How the withdrawn program worked is kept for reference in the guide to the delinquent FBAR submission procedures.
What If the Foreign Income Was Never Reported?
Then a reasonable-cause statement is the wrong tool, and filing the FBARs alone becomes a quiet disclosure, the one move the IRS has warned against. The correct lane is streamlined filing: three years of amended returns, six years of FBARs, and a signed non-willful certification, with a 5 percent penalty for U.S. residents and 0 percent for those meeting the non-residency test. The program terms sit on the IRS streamlined procedures page.
Case study: A retired teacher came to Ed Parsons CPA ready to self-file through the delinquent procedures. Four accounts, peak balance $268,000. The reconciliation found term-deposit interest that never reached Schedule B, about $1,900 a year, roughly $9,500 over five years. Wrong lane entirely.
We moved her to the domestic streamlined track instead: three amended returns picking up about $7,000 of income, six FBARs, and a 5 percent penalty of roughly $9,500 on the highest year-end balance. Against non-willful exposure of about $99,000 across six reports, the Streamlined Filing CPA Package closed the file at a known number. There has been no examination to date; the procedures do not come with a closing letter. Results depend on your facts.
What Are Acceptable Reasons for Filing an FBAR Late?
The statute itself carves out reasonable cause. Under 31 U.S.C. 5321(a)(5)(B), a non-willful penalty does not apply where the violation was due to reasonable cause and the account balances are properly reported on the late FBAR.
Reasons that hold up follow a pattern. Recent immigration with no exposure to U.S. information reporting. A preparer whose annual organizer never asked about foreign accounts. Inherited accounts, or signature authority over an employer account you never thought of as yours. Serious illness during the filing window. Records held abroad and genuinely out of reach.
Reasons that fail follow a pattern too. A questionnaire that did ask, answered no. Moving funds after learning of the rules. Anything that reads as not wanting the account seen.
As I tell clients drafting a first explanation: “The IRS does not penalize honest confusion, it penalizes convenient confusion. An acceptable reason is specific, dated, and consistent with your returns. A vague one reads like a strategy.”
What separates an accepted file from a rejected one is usually wording, sequence, and dates. That is judgment work, not template work.
What Does a Reasonable-Cause Statement for a Late FBAR Need to Say?
There is no cover letter and nothing to mail. The explanation goes on the FBAR itself. Page one of FinCEN Form 114 asks why the report is late and offers a drop-down list of reasons. If none of them fits, you choose “Other” and get a text box of 750 characters. That box is the whole statement FinCEN receives.
Reasonable cause has a legal meaning, and it is stricter than most people expect. The IRS manual takes the test from the courts: a person has reasonable cause for an FBAR violation when the violation happened despite ordinary business care and prudence. Not knowing about the form is where the analysis starts, not where it ends. The question is what a careful person in your position would have done, and whether you did it.
A statement that works answers five things, briefly and with dates:
- Which accounts existed and how you came to have them.
- What you understood about U.S. reporting at the time, and why: who prepared your returns, what they asked, and what you told them.
- The specific event that showed you the report was required, and when it happened.
- What you did next, and how quickly.
- That the income from the accounts was reported and the tax paid, year by year.
Then it has to survive a comparison with your own file. Schedule B of your return asks every year whether you had a foreign account. A “no” in that box sits badly beside a statement saying you told your preparer everything. An examiner reads the statement against the returns, the preparer’s organizer and the account-opening records, and a statement that conflicts with any of them is worse than no statement.
This is why a sample letter is the wrong starting point. A borrowed paragraph describes someone else’s facts, and 750 characters leaves no room for filler. The longer account, with the documents behind each sentence, belongs in your own file in case the IRS asks. Writing the short version without having built the long one is how statements end up vague.
One more distinction matters. Reasonable cause is a harder standard than the non-willful standard used in streamlined filing. Carelessness is non-willful, but it is not reasonable cause. If income also went unreported, the document that matters is not this statement at all. It is the sworn certification in a streamlined submission, Form 14654 for U.S. residents.
How Do You Decide Which Option to Use?
One question starts the tree: is every dollar of foreign income already on your filed returns, with the tax paid?
Yes, and no IRS contact: File the late FBARs with a reasonable-cause statement. No program guarantees the result since the delinquent procedures were withdrawn. The statement and your returns carry it.
No, and your conduct was non-willful: Streamlined filing. Amended returns plus certification. 5 percent domestic, 0 percent foreign.
Facts lean willful, or the IRS already contacted you: Neither program. Representation first, filings second.
Where your conduct sits on the willful or non-willful line is the hinge of that third branch, and it is not a self-serve call.

The first branch of the chart still names the Delinquent FBAR Submission Procedures, which the IRS has withdrawn. The route for that branch is now the reasonable-cause statement described above.
Frequently Asked Questions
My Take on Late FBAR Files
The fear economy around FBAR penalties is real. Plenty of marketing quotes the $165,353 willful number at people whose facts would never support willfulness, then sells them a heavier program than they need. The opposite failure is the forum advice to file quietly because nobody checks. Both get the same thing wrong: the lane is decided by your returns, not your nerves.
The underrated move is the same one I give every late filer: reconcile first. Six years of returns against every foreign statement, before anything is transmitted. Ten minutes with Schedule B answers the only question the decision tree asks.
If I were the reader, I would run the tree honestly, pick the lane my facts support, and never split the difference with a quiet disclosure. At Ed Parsons CPA, IRS account work is the core of the practice.